Your paycheck hits the same account it always did. It just doesn’t stretch as far.
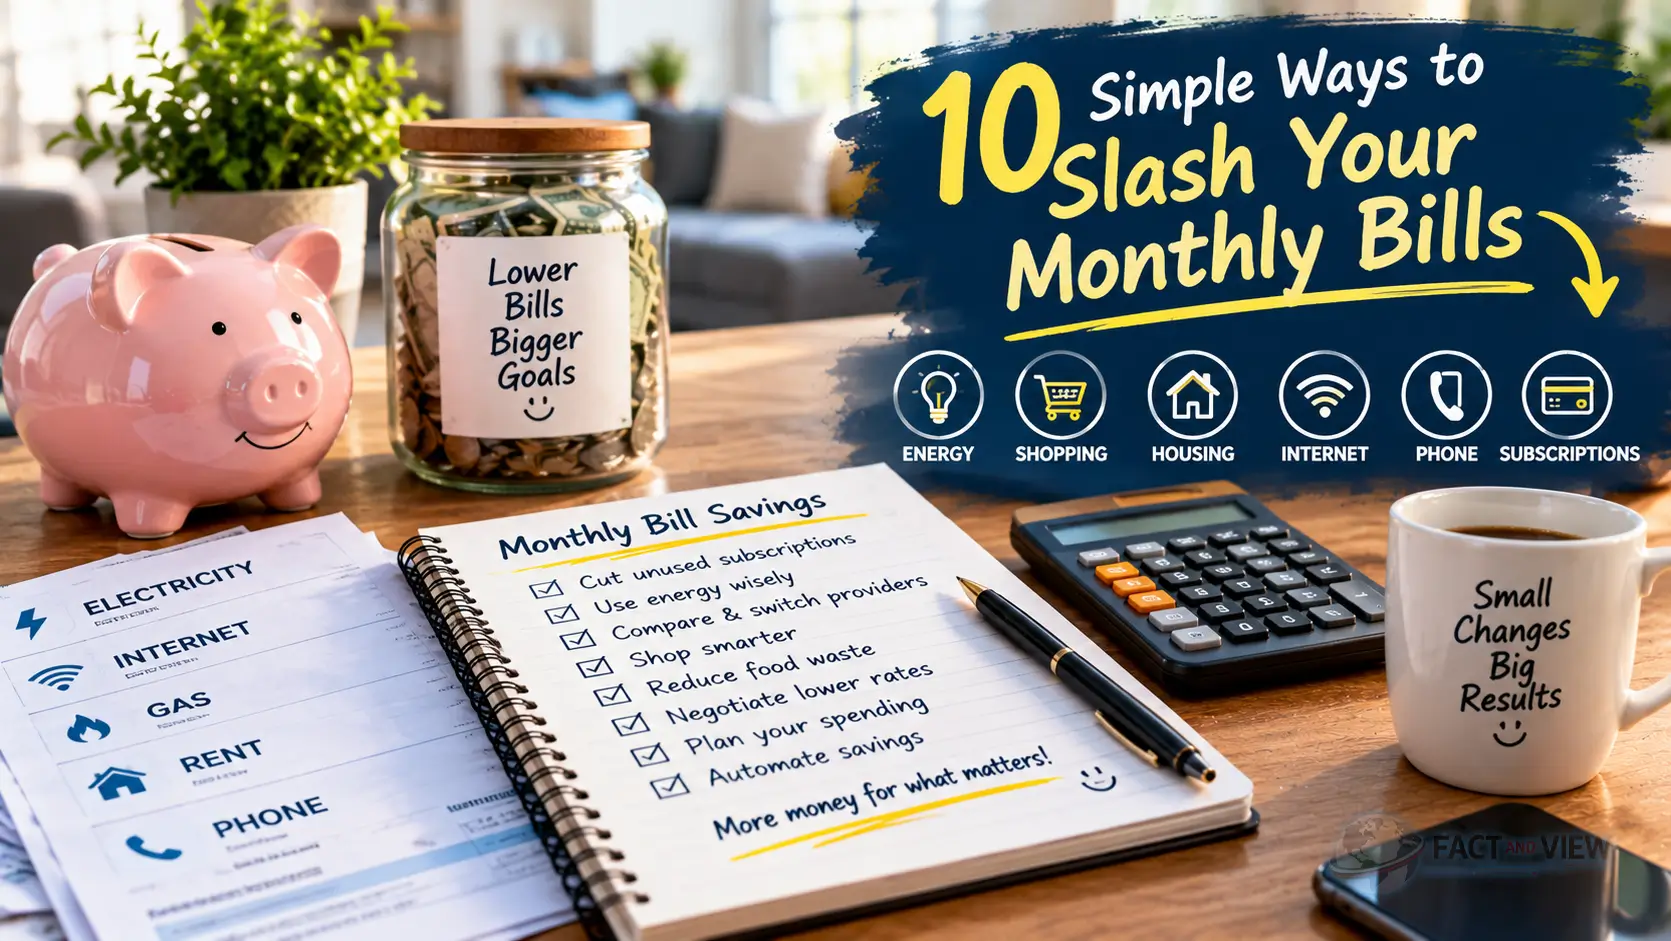
Between rent, groceries, gas, and whatever your streaming lineup costs these days, the average household is bleeding money in places it never used to. The good news: most of that leak is fixable in a weekend, not a year. Here are 10 moves that can put real cash back in your pocket this month.
1. Call and negotiate your recurring bills
Phone, internet, and cable companies expect you to call and complain. Budget for it.
- Ask for the retention department, not customer service
- Say “I’m thinking about canceling” out loud
- Mention a competitor’s price if you have one
Don’t want to make the call yourself? Apps like Experian BillFixers or Billshark negotiate for you and take a cut of what they save.
Typical win: $10 to $30 off your internet or cable bill, every month, for just one phone call.
2. Audit your subscriptions (you’re probably wrong about the total)
Most people guess they spend about $86 a month on subscriptions. The real number, per C+R Research, averages $219 a month. Gen Z runs even higher, closer to $377.
- Pull up your last two bank statements
- Highlight every recurring charge
- Cancel anything you haven’t opened in 30 days
Apps like Rocket Money or your bank’s own spending tracker will do this scan for you in under five minutes.
Related reading: New US Laws in 2026: What They Mean for Americans — the OBBBA provisions that did and did not pass, including the credit card rate cap that was proposed but not enacted.
3. Switch your cell phone to a discount carrier
Verizon, AT&T, and T-Mobile all run on the same towers as the budget brands that lease space on their networks.
- Mint Mobile, Visible, and Tello typically run $25 to $35 a month
- Same coverage, same 5G, no two-year contract
- Most let you keep your number and bring your own phone
Switching from a $90 unlimited plan to a $30 MVNO plan can save $720 a year, without changing a single habit.
4. Shop your car and home insurance every renewal
Insurance isn’t loyalty-rewarded. It’s the opposite.
The average full-coverage car insurance policy runs about $2,240 a year nationally, but that number swings hard by state, and even by zip code. Carriers quietly raise renewal rates on customers who never shop around.
- Get three quotes before every renewal, not just one
- Bundle home and auto with the same insurer for a discount
- Raise your deductible if you have savings to cover it
A 10-minute comparison can save $300 to $600 a year, sometimes more.
5. Move your savings into a high-yield account
If your savings sits at a big-bank branch, it’s probably earning next to nothing. The national average savings rate is about 0.39% APY, per the FDIC.
Online high-yield savings accounts are paying 4% APY or more right now, no fees, no minimums at most banks.
| Account Type | Typical APY | On $5,000 saved |
|---|---|---|
| Big-bank savings | ~0.39% | $19.50/year |
| High-yield online savings | ~4.2% | $210/year |
| Checking account | ~0.01% | $0.50/year |
Same risk. Same FDIC insurance. Just a better number.
6. Use cashback apps for groceries you’re already buying
This one costs zero extra effort.
- Ibotta and Fetch pay cash for scanning receipts after you shop
- Rakuten pays cashback on gas, Target, and Walmart purchases
- Stack store loyalty discounts on top for double savings
None of these change what’s in your cart. They just refund part of what you were already spending.
Related reading: What Happens If US Debt Keeps Rising? — the fiscal context that is keeping the Fed frozen and APRs elevated simultaneously.
7. Call your credit card company and ask for a lower rate
The average credit card now charges 21% APR, according to the Federal Reserve. On a $5,000 balance, that’s over $1,000 a year in interest alone.
- Call and ask directly for a lower APR
- Mention your on-time payment history
- If they say no, ask about a 0% balance transfer card
A good credit score makes this call much easier. Check yours free through your card issuer or Credit Karma before you dial.
8. Trim your energy bill without sweating through summer
Utility companies count on you never checking your usage.
- A smart thermostat can cut heating and cooling costs by 10 to 15%
- Run laundry and dishwashers during off-peak hours
- Ask your utility about a budget billing plan to flatten seasonal spikes
- Look up LIHEAP, a federal program that helps low-income households cover energy costs
9. Meal plan around what’s already on sale
Food waste is one of the sneakiest budget leaks there is.
- Check the weekly flyer before you plan meals, not after
- Buy store brands for staples like flour, pasta, and canned goods
- Batch-cook one big meal and portion it for the week
The average household throws out close to $1,500 worth of food a year. Even cutting that in half adds up fast.
10. Automate a small savings transfer every payday
This isn’t about willpower. It’s about never seeing the money in the first place.
- Set an automatic transfer of $25 to $50 per paycheck into savings
- Use a round-up app like Acorns to invest your spare change
- Route it into a Roth IRA or 401(k) if retirement savings is the real goal
Small and automatic beats large and occasional, every time.
The bottom line
None of these ten moves require a side hustle or a spreadsheet obsession. Pick three this week. Negotiate one bill, cancel one subscription, move your savings to an account that actually pays you.
That alone can free up $100 to $200 a month, money that’s currently going nowhere.
Save this post to your budgeting board on Pinterest so you’ve got it next time a bill renews. Or drop your email below for more no-fluff money tips, delivered before the next price hike catches you off guard.