The average American now pays $2,240 a year for full-coverage car insurance, according to Insurify’s mid-2026 rate data. That number has climbed fast since 2022, and it’s not evenly spread. Your neighbor’s bill could be hundreds of dollars different from yours, even with the same car.
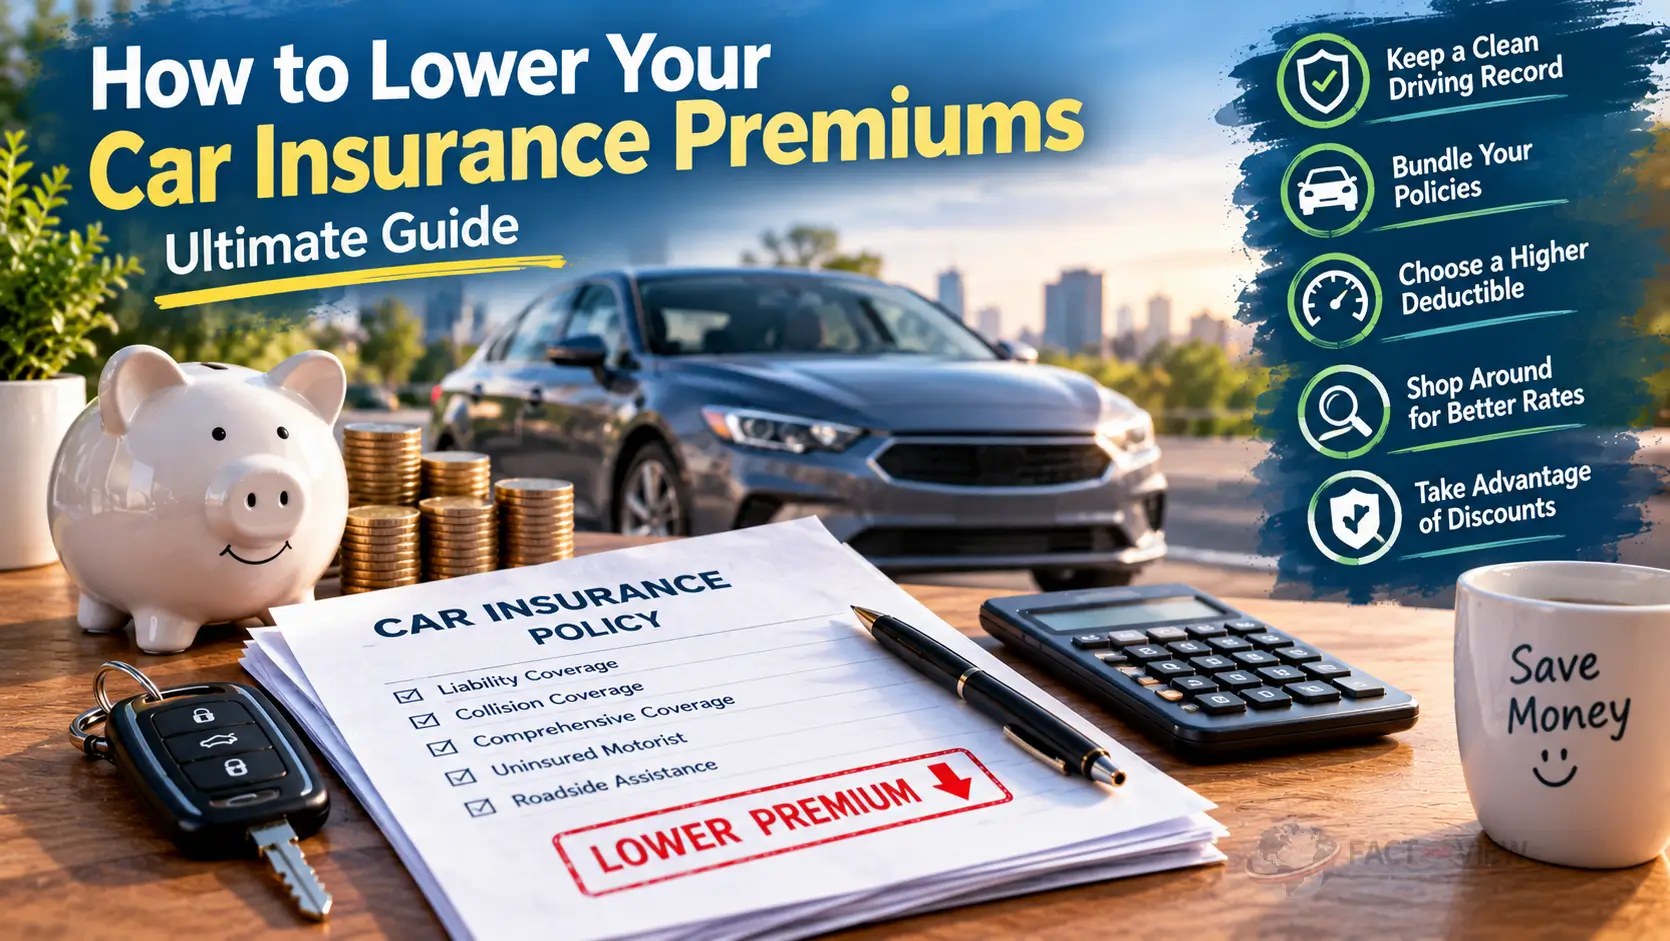
Here’s the part most people miss: a lot of that gap comes down to choices you control. Deductible level, which company you use, which discounts you’ve actually claimed. None of it requires a finance degree. Let’s break down what actually moves the number.
Raise your deductible (the single biggest lever)
Your deductible is what you pay out of pocket before insurance kicks in on a claim. Raise it, and your monthly premium drops.
- Going from a $200 to $500 deductible can cut premiums 15% to 30%, per the Insurance Information Institute
- A $1,000 deductible can save 40% or more on the collision and comprehensive portion
- A more recent NerdWallet analysis found smaller but still real savings, around 10% moving from $250 to $500
The catch: you need that deductible amount sitting in an emergency fund if you ever file a claim. Don’t raise your deductible past what you could actually cover tomorrow.
Shop your policy every single renewal
Insurance companies don’t all price risk the same way. One might flag your zip code as high-risk. Another might barely notice it.
- Get quotes from 3 to 5 companies before you renew, not just one
- Ask your current insurer to match a competitor’s quote before you switch
- Remember: rates vary heavily by state, so a national average means very little for your actual bill
Loyalty rarely pays off here. Carriers often raise renewal rates quietly on customers who never shop around.
Take a defensive driving course
This one’s a few hours of your weekend for a discount that can last years.
- Most insurers offer 5% to 20% off for completing an approved course, per Policygenius
- GEICO offers up to 10% off for eligible policyholders
- AARP members can get up to 5% off through the AARP Smart Driver course
Check with your insurer first. Not every course qualifies, and the discount rules vary by state.
Stack every discount you actually qualify for
Most drivers leave money on the table simply by not asking.
| Discount type | Typical savings | How to claim it |
|---|---|---|
| Bundling home + auto | 5% to 25% | Ask your current insurer for a quote |
| Good student (under 25) | 10% to 15% | Submit a transcript showing a B average or higher |
| Low annual mileage | 5% to 15% | Report actual miles driven, not an estimate |
| Telematics / safe-driving app | Up to 30% | Enroll in your insurer’s monitoring program |
None of these stack automatically. You usually have to call or fill out a form.
Know how your credit score factors in
In most states, insurers use a credit-based insurance score as part of your rate.
- California, Massachusetts, and Hawaii ban this practice entirely
- Everywhere else, a higher credit score typically means a lower premium
- Paying down high-interest debt, like the average 21% APR credit card balance, according to the Federal Reserve, can help your score and your insurance bill at the same time
If you’re working on your credit for other reasons, like qualifying for better rates elsewhere, this is a quiet side benefit.
Rethink full coverage on an older car
If your car is worth $3,000 and full coverage costs $1,200 a year, the math stops making sense.
- Look up your car’s actual cash value before your next renewal
- If the value is low, dropping collision and comprehensive may save more than it risks
- This only works if the car is fully paid off; a lender will require full coverage on a financed vehicle
This move pairs naturally with anyone already managing a car payment that’s stretching the monthly budget, since a paid-off car has the most flexibility here.
One more place to check: your home insurance
Car insurance rarely moves in isolation. If your premiums feel high across the board, rising home insurance costs are often part of the same budget squeeze, and bundling the two is frequently where the biggest single discount hides.
The bottom line
Pick two moves from this list today: raise your deductible if your emergency fund can cover it, and get three competing quotes before your next renewal. That combination alone typically beats anything else on this list.
Save this guide to your car or budgeting board on Pinterest for your next renewal date. Or sign up for the newsletter for more straight-talk money moves, no upsells, no fluff.